September 2026 Performance Synopsis
Technology hardware had September almost to itself, opening a roughly 30-percentage-point spread between the best and worst thematic portfolios. Testing & Inspection Equipment led at 12.76%, followed by Electronic Components (10.88%), Mobile Devices & Technology (10.00%), Measuring Instruments (9.95%) and Radio Frequency Technology (9.75%), driven by AI chip production, TSMC's advanced-packaging build-out and Apple's iPhone Duo foldable. The strength was narrow rather than broad: 212 of 243 global major themes fell, leaving a hardware corridor in an otherwise risk-off market.
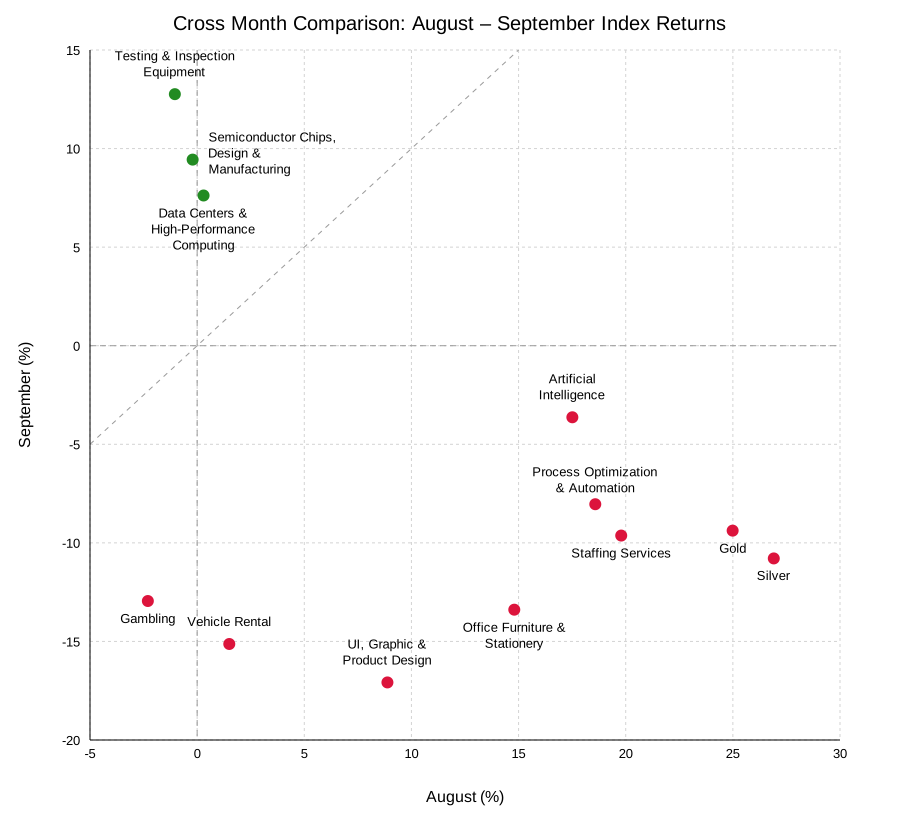
The cross-month picture was a near-complete rotation. August's leaders unwound—Silver swung from 26.91% to -10.79%, Gold from 24.99% to -9.38% and Staffing Services from 19.79% to -9.63%—while Process Optimization & Automation (18.58% to -8.04%) and Artificial Intelligence (17.51% to -3.63%) gave back their gains. August's laggards went the other way: Semiconductor Chips, Design & Manufacturing moved from -0.21% to 9.44% and Data Centers & High-Performance Computing from 0.30% to 7.62%—investors paying for AI infrastructure, not AI applications, the reverse of August. Regionally, CN supplied all three leaders, with Genomics & Gene Editing (17.77%), Innovation & Development Solutions (15.49%) and Real Estate Services (10.55%), while Non-Food Consumer Packaging fell 22.57% in EMEA, Industrial & Specialized Gas 14.44% in CN and Accounting & Auditing 13.72% in the US.
The losses landed on design, discretionary and niche themes. UI, Graphic & Product Design was worst at -17.08% as AI image generation reached production quality, while Vehicle Rental (-15.13%) fell on a lack of catalysts and the arrival of robotaxis in London. Art & Photography (-13.78%) suffered from political hostility to contemporary art and smartphone substitution, and Soundproofing Materials (-13.23%) and Gambling (-12.95%) were also among the worst, the latter on a wave of prediction-market lawsuits. A Fed rate rise and a stronger dollar weighed on the wider market: Private Equity fell 12.64%, Restaurants, Bars & Cafes 12.17% and Nuclear Energy 8.79%, while Oil & Petroleum slipped 3.46%.
Three themes are on the radar heading into October: EUV Systems and Technology, after Samsung and TSMC committed to ASML's High-NA machines and a 12-inch photomask initiative widened the supplier opportunity; Advanced CCS Development and Infrastructure, with Europe's first full cross-border CCS value chain now operating; and Secure Cryptographic Key Management, as a CISA and G7 post-quantum call to action and NIST's retirement of FIPS 140-2 certificates drive HSM refresh cycles.
Best Performing Themes
September's leaders were a technology-hardware story. Testing & Inspection Equipment led at 12.76% as AI chip production and TSMC's advanced-packaging expansion lifted demand for wafer inspection and metrology, with chip-equipment stocks outperforming even Nvidia. Electronic Components (10.88%) gained on Analog Devices' $1.35bn deal for Alif Semiconductor, SK Hynix's talks over an Intel tie-up and record South Korean exports. Mobile Devices & Technology (10.00%) rode Apple's iPhone Duo foldable and $100 iPhone 18 Pro price rises, Measuring Instruments (9.95%) the health-sensor upgrades in the Apple Watch Series 12 and Ultra 4, and Radio Frequency Technology (9.75%) nearly $196m of US Army spectrum contracts.
Worst Performing Themes
September's losers were concentrated in design, discretionary and niche themes. UI, Graphic & Product Design fell 17.08% as OpenAI's image models reached professional quality and Adobe's soft revenue outlook revived fears of AI disruption. Vehicle Rental (-15.13%) slid on sector rotation and robotaxi competition, and Art & Photography (-13.78%) on the Kennedy Center's removal of the 'Blue' sculpture, a Renoir theft and the iPhone 18 Pro's camera upgrades. Soundproofing Materials (-13.23%) faced higher Treasury yields and noise-cancelling alternatives, while Gambling (-12.95%) was hit by lawsuits against Polymarket and Kalshi and Brazil's proposed online casino ban.
Cross-Month Comparison
September turned August's table upside down. Silver, Gold, Staffing Services and Process Optimization & Automation, all among August's strongest themes, posted steep losses, and Office Furniture & Stationery gave back almost all of its August gain. The hardware complex moved the other way: Testing & Inspection Equipment, Semiconductor Chips, Design & Manufacturing and Data Centers & High-Performance Computing were flat or negative in August and among September's few winners. Artificial Intelligence slipped even as the hardware beneath it rallied, while Vehicle Rental and Gambling saw losses accelerate sharply.
Interesting Themes from Cross-Month Comparison
The sharpest reversals came in precious metals. Silver (August 26.91% to September -10.79%) and Gold (24.99% to -9.38%) unwound as the Fed raised rates for the first time in three years and the dollar strengthened. Semiconductor Chips, Design & Manufacturing went from a flat August (-0.21%) to 9.44% on the ASML and TSMC 12-inch photomask initiative and Intel's High-NA EUV milestone. Office Furniture & Stationery (14.80% to -13.39%) fell on heavy discounting and competition from budget entrants, and Staffing Services (19.79% to -9.63%) on Korn Ferry's soft guidance and AI hiring tools.
Region Best and Worst Performing Themes
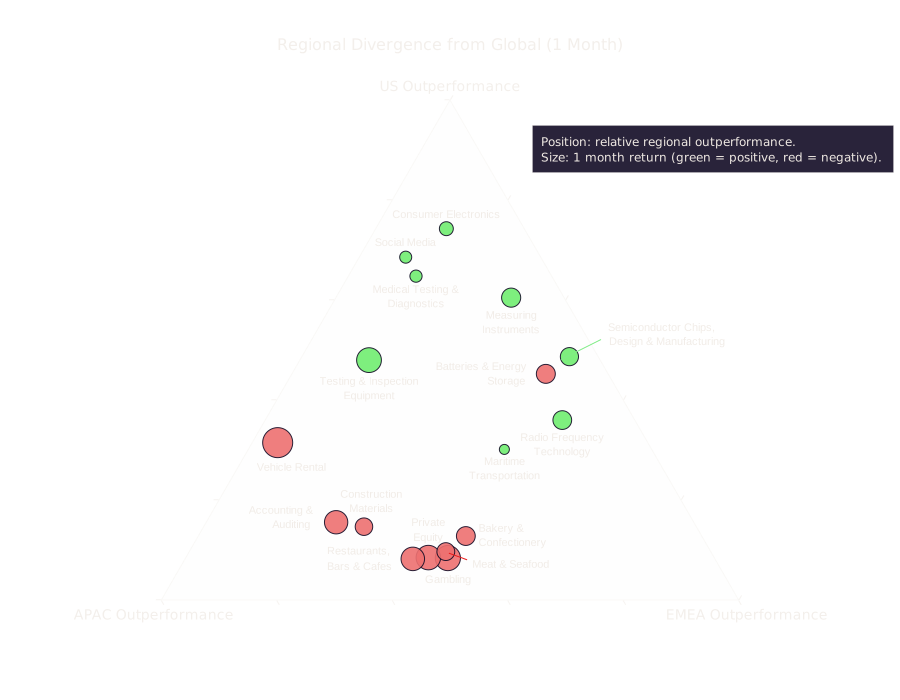
China led the regional tables. Genomics & Gene Editing gained 17.77% in CN after Anthropic's Claude identified a CRISPR-like enzyme system, while Innovation & Development Solutions rose 15.49% on heavy AI infrastructure investment and venture funding, and Real Estate Services 10.55% on recovering deal volumes. On the downside, Non-Food Consumer Packaging fell 22.57% in EMEA as the EU's packaging regulation began to apply, Industrial & Specialized Gas lost 14.44% in CN on Elliott's stake in Air Liquide and heavy hydrogen spending, and Accounting & Auditing declined 13.72% in the US on the SEC's audit-rule rollback and AI-driven fee compression.
Themes on the Radar
EUV Systems and Technology
High-NA EUV lithography moved from a single-customer technology to an industry roadmap in one week of September. Samsung and TSMC committed to ASML's High-NA EUV machines, with Samsung planning to use them from 2028 for DRAM and TSMC expecting to adopt them in 2030 for advanced chips. Separately, ASML and TSMC set up an industry-wide initiative on 7 September to move to 12-inch photomasks, which widens the opportunity to mask and materials suppliers. [345, 346]
Advanced CCS Development and Infrastructure
Europe's first full cross-border CCS value chain started operating in September. Yara's Sluiskil plant can capture and liquefy up to 800,000 tonnes of CO₂ a year from ammonia production, and Northern Lights vessels will ship it to Øygarden in Norway for storage 2,600 metres below the seabed. The heads of government present at the launch signal political backing for a wider European carbon-management market. [347, 348]
Secure Cryptographic Key Management
The move to post-quantum cryptography got a coordinated policy push in September. CISA and the G7 Cyber Security Working Group released a call to action urging organisations and governments to start transitioning to post-quantum cryptography to protect sensitive data, authentication systems and critical assets. Compliance deadlines add urgency: on 21 September 2026 NIST moved all remaining FIPS 140-2 certificates to Historical status, after which those modules no longer satisfy federal procurement requirements. Together these drive demand for key-management and HSM refresh cycles. [349, 350]
Commodities Equity Performance Dashboard
This dashboard provides performance analytics for global equities with exposure to commodities-related themes in Theia Insights Industry Classification (TIIC), grouped by Industry (level two).
Regional Thematic Performance Overview (Top and Bottom Performing Themes by Region)
This analysis showcases the top three outperforming and underperforming investment themes across major regions, utilising the TIIC framework. By examining how identical themes perform differently across geographical markets, this breakdown illuminates the critical impact of regional economic dynamics, regulatory landscapes and geopolitical developments on thematic investment returns.
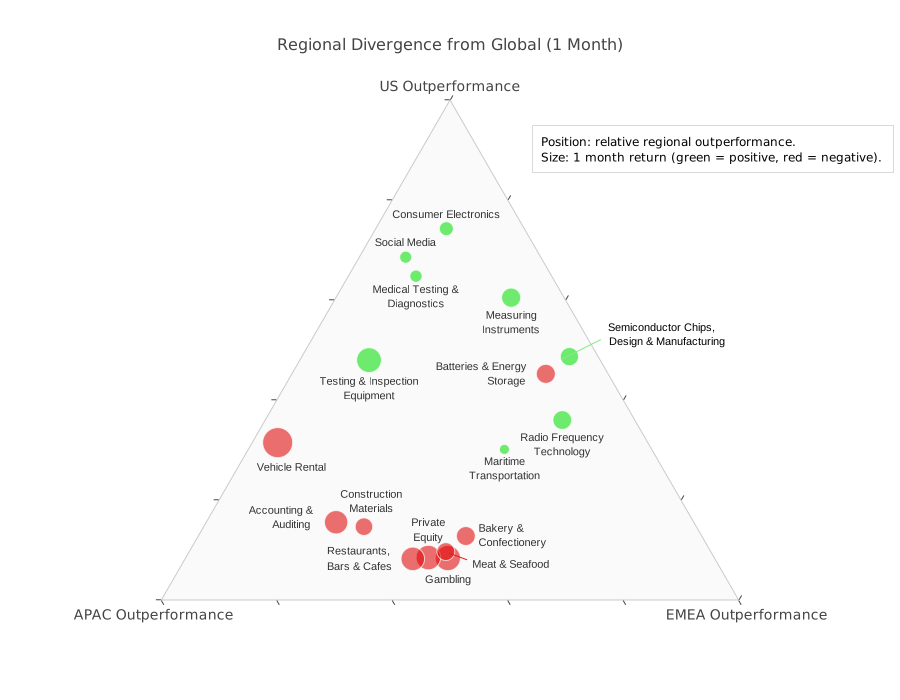
Regional Performance Divergence vs Global
Each point's position indicates the relative regional outperformance compared to the global average. The analysis includes tradable portfolios in all three regions, excluding themes that lack sufficient market presence or liquidity.
Global Sector Thematic Performance (Top and Bottom Performing Themes by Sector)
This dashboard examines thematic investment performance organised by the top-level sectors within the TIIC framework. For each sector we report the top three and bottom three performing themes. By grouping themes under their primary sector classifications, this analysis reveals how broad sectoral trends influence underlying thematic opportunities and risks.
Looking Ahead
September's rotation into technology hardware came against a hawkish backdrop: a Fed rate rise, a stronger dollar and higher Treasury yields pushed most themes lower and unwound August's precious-metals rally. Whether Testing & Inspection Equipment, Semiconductor Chips, Design & Manufacturing and Data Centers & High-Performance Computing can extend their gains depends on AI capex continuing to flow to equipment and components while the wider market stays risk-off.
The split within AI is the swing factor. Hardware strengthened while Artificial Intelligence and Process Optimization & Automation fell—the reverse of August—and whether that rotation holds will shape the coming month. EUV Systems and Technology, Advanced CCS Development and Infrastructure, and Secure Cryptographic Key Management are the emerging themes worth monitoring, tied to the lithography, carbon-management and post-quantum security build-outs respectively.